de-mauritius-2012-base · encoding recovery evidence
Unreviewed machine transcription. No legal review; currentness unknown. Noindex is not access control.
Treaty directory · Source supplements
Complete separate source supplements
The signing clause identifies German and English as equally authentic; both are supplied as separate machine transcriptions. No additional authentic language is identified in that clause. Unreviewed coordinate-based machine transcription of this original source edition only. Printed line breaks, hyphens and uncertain token spacing are retained, not silently corrected. Treaty preamble, closing formula, protocol and shared signatures are separate retained assets, not part of the last article. Full supplements: /review/de-mauritius-2012-base/. PDF page links identify pages, not verified paragraph correspondence. Signed 2011-10-07; consent law 2012-10-02; Gazette publication 2012-10-09; treaty entry into force 2012-12-07 (retained official-article audit evidence); general tax application from 2013-01-01 (BMF 2026 roster, not every tax-specific transition). Consent-law commencement 2012-10-10 is NOT treaty entry into force. Encoding-recovery method: only the source font code00 /space Unicode mapping U+0007 to U+0020 changed in a separately hashed derivative. CFF blank glyph, 278-unit advance, unchanged page content streams and 23/23 identical source/derivative page renders for this edition evidence this mapping. Word regrouping is logged; every nonspace character is conserved in sequence within its physical source line. No model-generated treaty wording and no OCR.
Currentness and later material
The integral protocol signed 7 October 2011 is retained separately. A LATER AMENDING PROTOCOL signed 29 October 2021 is NOT included or consolidated here. The 2026 roster records general application from 1 January 2023 and cites the entry notice BGBl. 2023 II No.50; the official article still displays ./. for protocol entry into force. Exact amendment entry date and tax-specific effect remain UNRESOLVED pending examination of that notice. Do not treat this base edition as current consolidated law. MLI and any other later changes are not exhaustively verified.
Evidence, not legal review
Original SHA-256: bd5b5aff9b41c4b21c0c62bc2e2b3ba2798236a1e1e886dec8f45ae3680426a4
Encoding derivative SHA-256: 8407be8b0437d40b031c41da7e1bb3a1d9351724d31293235370be6572d10c0c
17219 mapped blank-glyph occurrences; 2531 geometry-reconciled lines; 357 flagged text regions retained. Flags are not an exhaustive accuracy score. All wording remains unreviewed.
- encoding-recovered.pdf · SHA-256
8407be8b0437d40b031c41da7e1bb3a1d9351724d31293235370be6572d10c0c - raw-bbox.xhtml · SHA-256
9e680ed3f59f87b12e3617f350ca785a898d27ab50c06e6b4a002b35b62eeac4 - raw-layout.txt · SHA-256
9d77830badc1a06ad4c8365be8f5eeefd25a6ca9a815cffabf1a7779cb31c07a - repaired-bbox.xhtml · SHA-256
1d518d10c4807a89cf910ceb24b21c5f4e3cbbec203144dd3337ca4483a359df - repaired-layout.txt · SHA-256
a3b443377ffe5ac0aa3758f1a79f1766672e3e7b294110ce03b431781a8991f0 - encoding-transformations.json · SHA-256
3116334154d237e4e827c7fc23956aafb1fa6d1ef548e7f12bf4136eac87c72e - geometry-token-conservation.json · SHA-256
c9fc4d7f353feb6bbaab842fae02661dcc5676f9a207c9bf5c6b99577ae80393 - render-equality.json · SHA-256
790a88a22484324dc71d1667d9c061b1149b935f8a454b80a7b79cddae6beeb7 - independent-extraction-comparison.json · SHA-256
714b0479e3adf23ad2eec05aadbb38ec259c54708bc33ee4e9bcad75c5232f9a - independent-pypdf.txt · SHA-256
1268e8f940ab600b81ad3982e5ec7f8dcdc3d327de0e22535b2c2002eea56112 - uncertainties.json · SHA-256
e5ee1c640bfd866f2cde9cf70b591a31979d760c10c634c619807cd321b270ae - edition-audit.json · served privacy-redacted SHA-256
6c3d0b83c69ede1c662116edba80e9a7309de4d943f2ab406c29e146a5bedc31; sealed unredacted input SHA-256895652053c21810dd32d06c99ef684b1e319c1194279451c2c676df395c2c602; redaction manifest
Source glyph proof
Font object 26: /HZVHZU+HelveticaNeueLTW1G-Roman; encoded00 selects /space, width278/1000em; CFF space charstring fc080e contains only width/endchar and no outline. ToUnicode mapped it to U+0007. Derivative changes only that mapping to U+0020.
Font object 130: /WRVEWO+HelveticaNeueLTW1G-Roman; encoded00 selects /space, width278/1000em; CFF space charstring fc080e contains only width/endchar and no outline. ToUnicode mapped it to U+0007. Derivative changes only that mapping to U+0020.
Original physical page evidence
These images identify full physical PDF pages, not verified paragraph correspondence. Accessible extracted text is provided beside each image; it is machine evidence.
Physical PDF page 1
1050 beschlossen: blatt zu verkünden. Berlin, den 2. Oktober 2012
Physical PDF page 2
Die Bundesrepublik Deutschland und die Republik Mauritius – von dem Wunsch geleitet, ein Abkommen zur Vermeidung der Doppelbesteuerung und der Steuerverkürzung auf dem Gebiet der Steuern vom Einkommen zu schließen –
1051 The Federal Republic of Germany and the Republic of Mauritius, Desiring to conclude an Agreement for the avoidance of dou- ble taxation and of tax evasion with respect to taxes on income,
Physical PDF page 10
Betrag, den Schuldner und Nutzungsberechtigter ohne diese Beziehungen vereinbart hätten, so wird dieser Artikel nur auf den letzteren Betrag angewendet. In diesem Fall kann der über - steigende Betrag nach dem Recht eines jeden Vertragsstaats und unter Berücksichtigung der anderen Bestimmungen dieses Abkommens besteuert werden.
1059 amount which would have been agreed upon by the payer and the beneficial owner in the absence of such relationship, the pro- visions of this Article shall apply only to the last-mentioned amount. In such case, the excess part of the payments shall remain taxable according to the laws of each Contracting State,
Physical PDF page 19
1068 b) bei den übrigen Steuern auf die Steuern, die für Zeiträume ab dem 1. Januar des Kalenderjahrs erhoben werden, das auf das Kündigungsjahr folgt. Maßgebend für den Zeitpunkt des Außerkrafttretens dieses Ab- kommens ist der Tag des Eingangs der Kündigung bei dem an-
b) in the case of other taxes, in respect of taxes levied for periods beginning on or after the first day of January of the calendar year next following that in which notice of termina- tion is given. The date of receipt of such notice by the other Contracting State shall determine the date of termination of this Agreement.
Physical PDF page 20
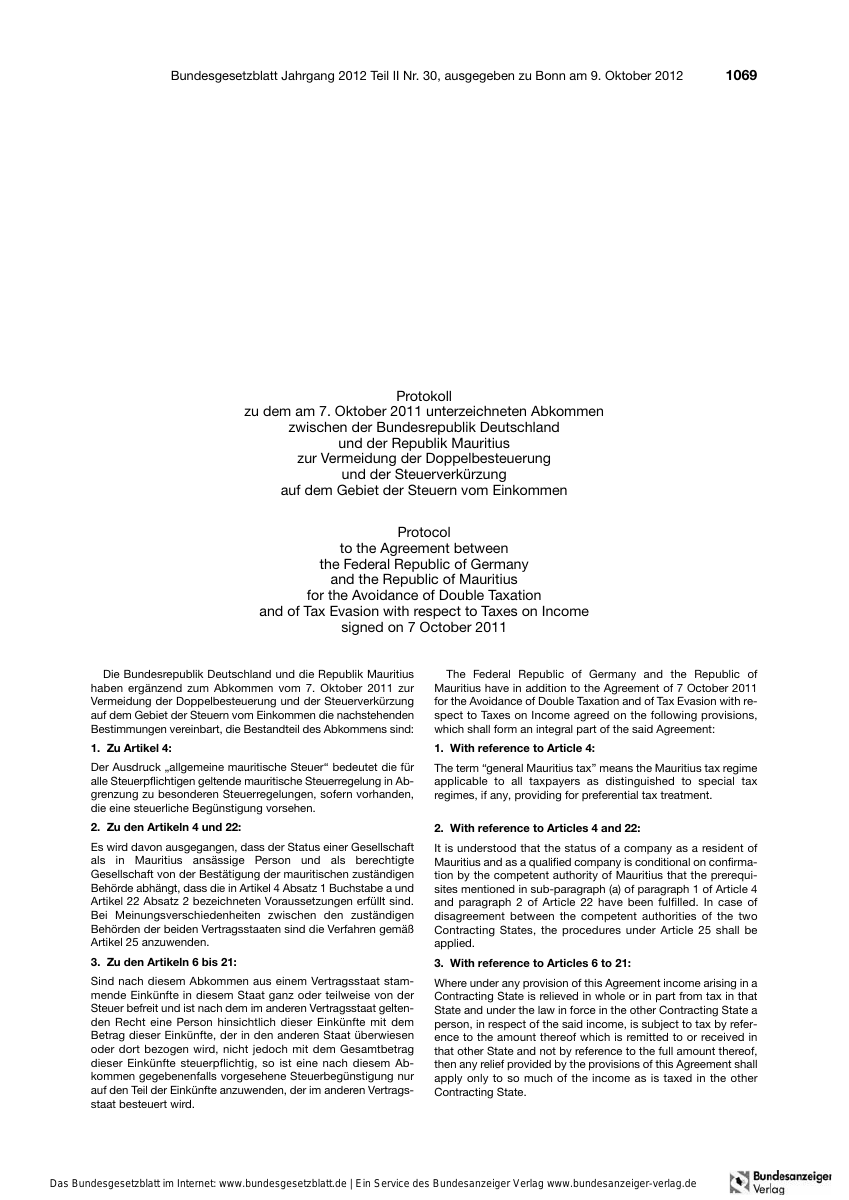
Die Bundesrepublik Deutschland und die Republik Mauritius haben ergänzend zum Abkommen vom 7. Oktober 2011 zur Vermeidung der Doppelbesteuerung und der Steuerverkürzung auf dem Gebiet der Steuern vom Einkommen die nachstehenden Bestimmungen vereinbart, die Bestandteil des Abkommens sind: 1. Zu Artikel 4:
1069 The Federal Republic of Germany and the Republic of Mauritius have in addition to the Agreement of 7 October 2011 for the Avoidance of Double Taxation and of Tax Evasion with re- spect to Taxes on Income agreed on the following provisions, which shall form an integral part of the said Agreement: